Insights
What changed, and what it means for you.
The compliance calendar our clients run on, and sharp notes the moment the rules move. No filler.
Keep business and personal money in separate accounts
Mixing personal spending with business receipts makes every return harder to prepare and to defend. A separate account is the simplest fix.
When course fees, client payments and household spending all pass through one bank account, every transaction has to be sorted by hand before a return can be prepared. Items get missed, and personal credits can be mistaken for income. Your books are only as reliable as the account they are built from. A clean business account makes it easy to show which receipts are income and which payments are business expenses, if a question is ever raised. Open a current account used only for the business. Route all client and platform payouts into it, and pay business expenses from it. Move money to your personal account as a single, regular transfer rather than spending directly from the business
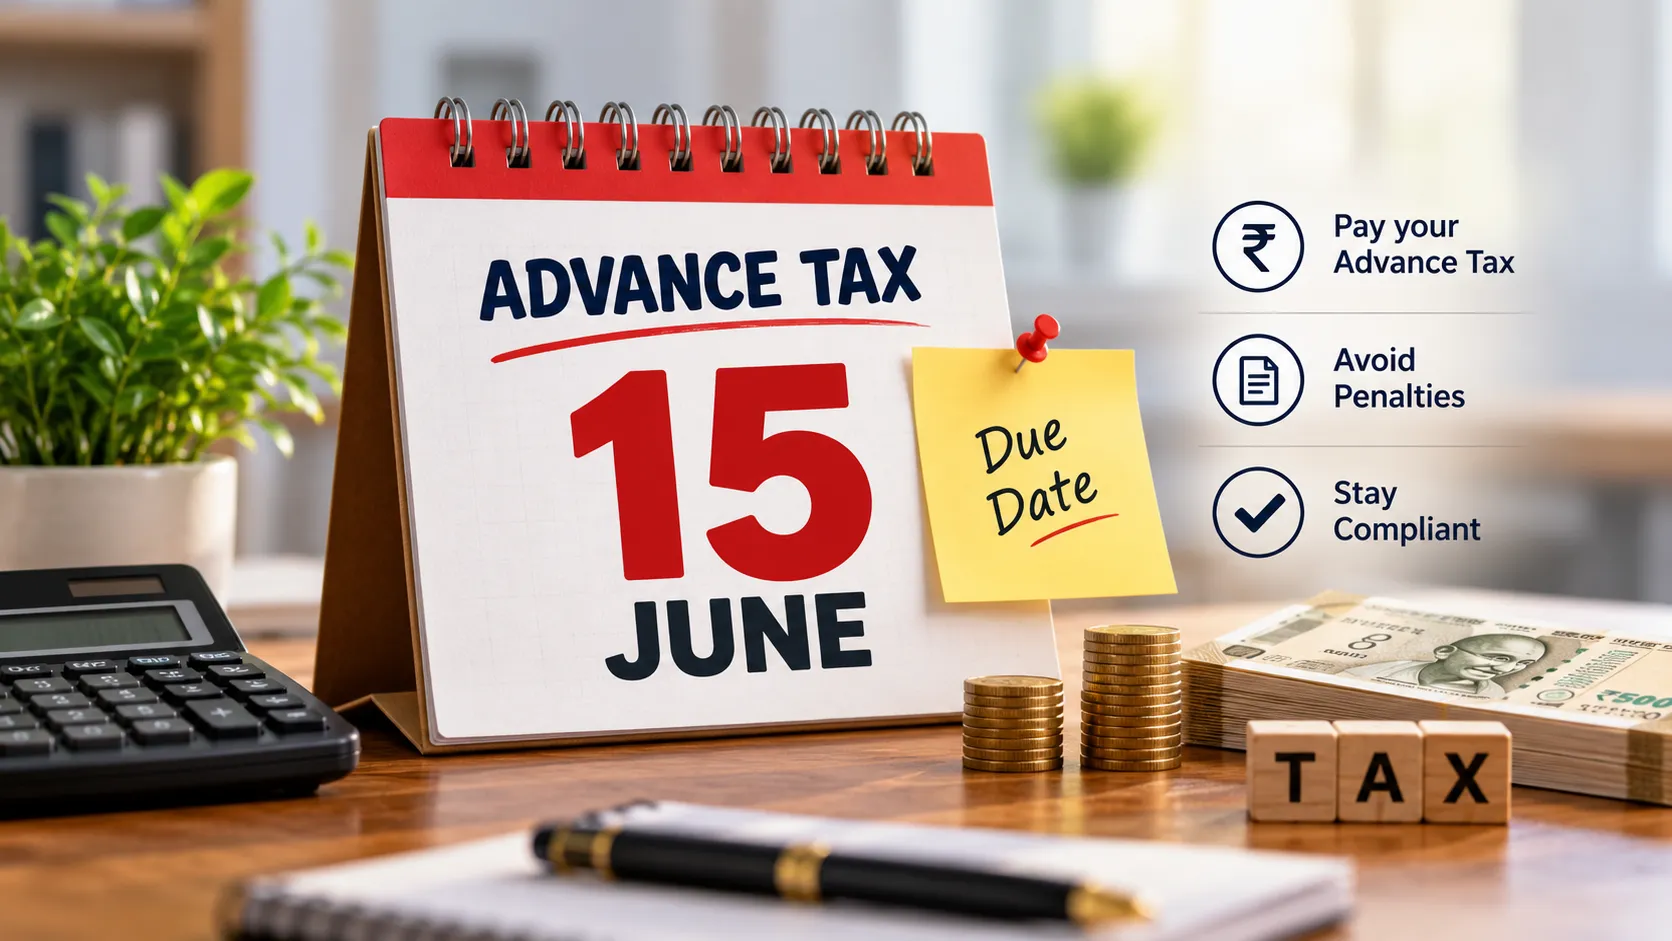
Advance tax: the 15 June instalment
Fifteen per cent of the year's estimated tax is due by mid-June. Shortfalls carry interest at one per cent a month.
Anyone whose tax for the year, after TDS, is expected to be ₹10,000 or more pays it in advance, in four instalments: 15% by 15 June, 45% by 15 September, 75% by 15 December and 100% by 15 March. Resident individuals aged 60 or over with no business income are exempt. Businesses and professionals under the presumptive schemes may pay the whole amount by 15 March. In June the year has barely begun. The estimate rests on last year's figures, the order book and judgement. Getting it roughly right matters: a shortfall in any instalment attracts simple interest at 1% a month on the amount short. Estimate from the first two months' actuals and last year's pattern, and revisit the estimate before
The Income-tax Act, 2025 is now in force
From 1 April 2026 the 1961 Act is replaced. Rates are largely unchanged; the vocabulary and section numbers are not.
The Income-tax Act, 2025 came into force on 1 April 2026 and replaces the Income-tax Act, Returns for the year ended 31 March 2026 are still filed under the old Act. The most visible change is the tax year. The previous year and assessment year are replaced by a single tax year that follows the financial year. Sections have been renumbered and consolidated, and many forms carry new numbers. For most businesses and individuals, rates, slabs and the substance of deductions continue broadly as before. The work is in updating references: in invoices that cite TDS sections, in agreements, in board resolutions and in internal policies. Check that accounting and payroll software has been updated
Exporting services? Renew your LUT before 1 April
A Letter of Undertaking lasts one financial year. Without a current one, IGST must be paid on exports and claimed back later.
Businesses that export services, from software and consulting to online courses sold to students abroad, can supply them without paying IGST by furnishing a Letter of Undertaking (LUT) in Form GST RFD-11 on the GST portal. An LUT is valid for one financial year. A new one is needed each year, and it should be in place before the first export invoice of that year. Exports made without a valid LUT are supplies on payment of IGST. The tax can be claimed back as a refund, but the money is locked up in the meantime, and the refund takes time and paperwork. Export of services also depends on payment being received in convertible foreign exchange, or in Indian rupees where the RBI permits, and on
Paying small suppliers late can cost you the deduction
Amounts owed to micro and small enterprises beyond the permitted period are not deductible until they are paid.
Since the year beginning 1 April 2023, amounts payable to micro and small enterprises registered under the MSMED Act are allowed as a deduction only when paid, if payment is made later than the time limit in that Act. The limit is 15 days from acceptance where there is no written agreement, and the agreed period where there is one, but never more than 45 days. An invoice from a registered micro or small supplier still unpaid past the limit on 31 March is added back to income for that year. The deduction is allowed in the year it is eventually paid. For businesses with many small suppliers, the effect on the year's tax can be significant. Ask suppliers for their Udyam registration status and
Input tax credit is what GSTR-2B says it is
Credit can only be claimed for invoices your suppliers have reported. Reconciling every month is the only way to keep it.
Input tax credit on purchases can be claimed only to the extent the supplier's invoices appear in your GSTR-2B for the period. An invoice the supplier has not reported, or has reported late or incorrectly, gives no credit that month, however genuine the purchase. Since October 2024 the Invoice Management System on the portal lets recipients accept, reject or keep pending each supplier invoice before GSTR-2B is finalised. Suppliers who file late, invoices recorded against the wrong GSTIN, and amendments that never reach the portal. Each is small; together they can be a meaningful share of the credit a business believes it has. Reconcile purchase records against GSTR-2B every month, before
The monthly calendar
7
TDS and TCS payment
Tax deducted in the previous month is deposited by the 7th (30 April for March deductions).
11
GSTR-1
Outward supplies for the previous month, for monthly filers.
13
IFF and quarterly GSTR-1
Invoice furnishing facility for QRMP filers, and the quarterly return after each quarter.
15
PF and ESI
Provident fund and ESI contributions for the previous month.
20
GSTR-3B
Summary return and payment of GST for monthly filers. QRMP filers pay by the 25th.
30
TDS certificates and challans
Form 16A and challan-cum-statements, where applicable for the month.
Dates shift when the department extends them. Clients on our accounting and compliance plans are reminded before each one; nobody needs to watch this page.
Annual dates
15 June, 15 September, 15 December, 15 March
Advance tax instalments — 15%, 45%, 75% and 100% of the estimated liability.
31 July
Income-tax return for individuals and others not subject to audit.
30 September
Tax audit report, where a tax audit applies.
31 October
Income-tax return for audited assessees.
31 December
GSTR-9 and GSTR-9C annual return and reconciliation for the previous financial year.
Company filings
AOC-4 and MGT-7 within 30 and 60 days of the annual general meeting.